from renting
to owning.
If you're paying $2,000 or $3,000 a month in rent, you might be closer to owning than you think. This guide walks you through every step of buying your first home in Greater Boston, from getting your finances ready to getting your keys.
I was born and raised in Roxbury, and I've been a licensed agent since 2019. The worries I hear most are losing out, overpaying, and affording the payment. This guide answers all three.
Buying a home is a marathon, not a sprint, and you don't have to run it alone.
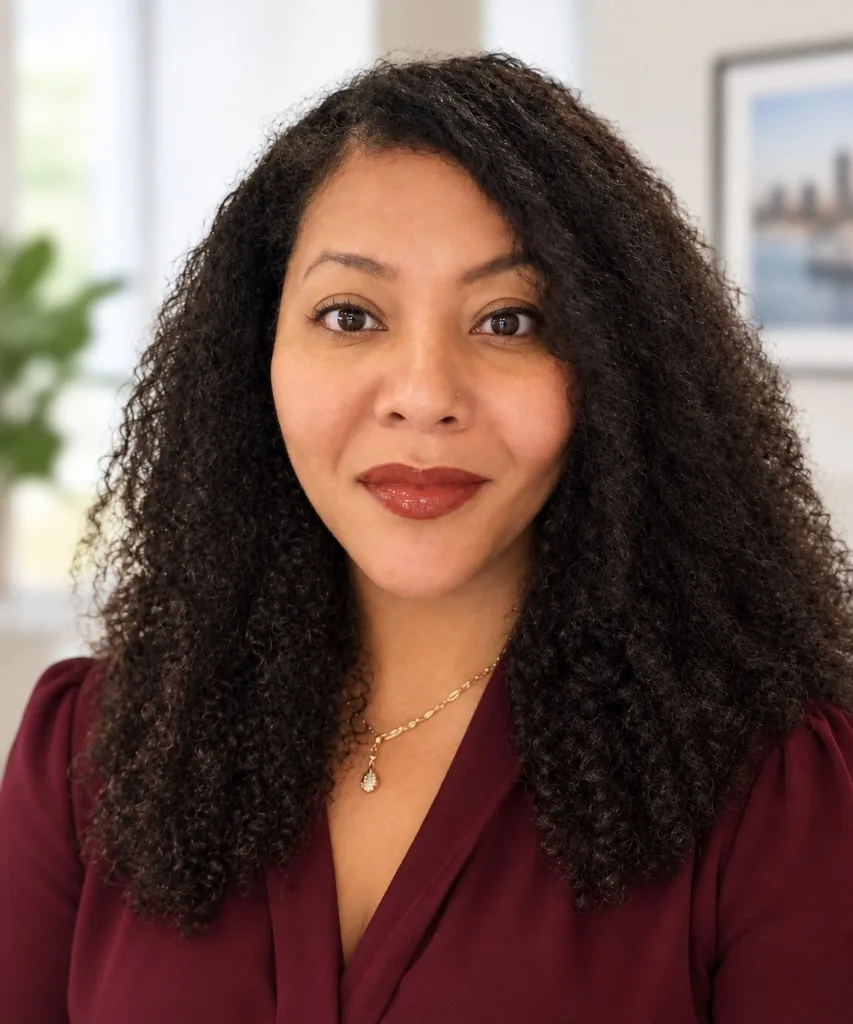
Marissa Amin
Licensed Real Estate Agent · Amo Realty
what you can count on.
I've helped Greater Boston buyers and sellers since 2019, across Norfolk, Suffolk, Middlesex, Plymouth, Bristol, Essex, and Worcester counties. You work with me directly, from your first call to closing day.
straight answers
I tell you what the market says, even when it isn't what we hoped to hear.
your number, not theirs
We build your search around the monthly payment you're comfortable with.
every page explained
We go over every document together before you sign anything.
one point of contact
I coordinate lenders, inspectors, and attorneys for you. You talk to me, not an assistant.
extras that come with me.
Introductions to lenders I trust, offers built on recent sales data, and help sorting out Massachusetts first-time buyer programs. Selling too? I manage both sides on one timeline. I also speak Thai.
“She made the home-buying experience feel effortless. She doesn't just show houses; she wins them.”
— Past Buyer Review
six steps to your keys.
Every buyer's timeline is different, but the steps always happen in this order.
your finances
Credit, savings, and a monthly payment you're comfortable with.
the offer
Offer to Purchase, your home inspection, then the Purchase and Sale Agreement.
pre-approval
Find out what you can borrow and which first-time buyer programs fit you.
appraisal & mortgage
Your lender confirms the home's value and commits to your loan.
the search
Sign your buyer agreement, pick your must-haves and towns, and start touring.
closing
Final walk-through, sign, and the keys are yours.
Days from accepted offer to your P&S, typically. Your inspection happens in between. Closing follows on the date we negotiate, set around your loan.
know where you stand.
You don't need perfect credit or 20% down to buy a home. You do need to know where you stand before you start.
check your credit
Free tools like Credit Karma show your score and report. Fix errors early, since disputes take time.
know your down payment
Some first-time buyer programs allow as little as 3% down, and some loans allow part of it to be a gift from family.
save for more than that
Your deposits, closing costs, and a cushion for after you move in.
pick your monthly number
Your lender tells you the most you can borrow. Only you decide what's comfortable. Include taxes, insurance, and condo fees.
What To Save For (Interactive Checklist)
Don't open new credit, finance a car, or change jobs while you're buying. Lenders recheck your finances right before closing, and a surprise can delay your loan.
get pre-approved first.
In this market, sellers want to see a pre-approval letter before they take your offer seriously. Get one before you start touring. I'm happy to introduce you to lenders I trust.
what they check
Credit, income, job history, debts, and savings. Expect pay stubs, bank statements, and two years of tax returns.
shop around
Compare the APR, fees, and programs, not only the rate. Every lender owes you a Loan Estimate within three business days.
it expires
Usually after 60 to 90 days, depending on the lender. If your search runs longer, your lender refreshes it.
Massachusetts First-Time Buyer Programs
No home owned in past 3 yrs| Program | What It Offers | Who It's For |
|---|---|---|
| MHP ONE Mortgage | 3% down on single-families, condos, and 2-families (5% on 3-families), with no private mortgage insurance | Income-eligible first-time buyers. Homebuyer class required. |
| MHP ONE+ | Up to $50,000 toward down payment and closing costs on top of ONE Mortgage. As little as 1.5% from your savings. | Buyers in 29 eligible communities, including Quincy, Lynn, and Framingham. Funding is limited. |
| ONE+Boston | ONE Mortgage plus extra down payment help from the City of Boston | Current Boston residents buying in Boston |
| MassHousing | Down payment assistance up to $30,000 at 0%, deferred until you sell or refinance, or up to $25,000 at 2% or 3% over 15 years | Income-eligible first-time buyers statewide. Homebuyer class required. |
| VA loans | Can allow 0% down | Eligible veterans and service members |
Some cities and towns offer their own down payment help, too. Program rules, income limits, and funding change often, so your lender will confirm what you qualify for today.
find the right home.
Now the fun part. Before we tour, we'll sort your list into must-haves and nice-to-haves. It keeps you from falling for a house that doesn't work for your life.
Questions To Think About
Which Type Of Home
condo
Less upkeep, plus monthly condo fees.
single-family
More space, and more maintenance.
2-family
Rent from your tenant helps pay the mortgage. Some programs allow a low down payment here, too.
Where my buyers are looking: I work all over Greater Boston, and I know Boston, Quincy, and the surrounding towns especially well. I grew up in Boston, so I know these neighborhoods from the inside. Each one has its own mix of prices, home styles, and commutes. Tell me what matters to you, and we'll narrow it down.
We'll sign a written buyer agreement before we tour. Since August 2024, agents who show homes through the MLS need one. It spells out what I'll do for you and how I'm paid. Commissions are negotiable, and I'll walk you through it.
the offer, the massachusetts way.
Buying here happens in two stages. When you find the one, I'll pull recent comparable sales so your price is based on data, not nerves. Then we go over every page together before you sign.
Your Offer Package
Offer to Purchase
The property, your price, your deposit, and key dates.
Contingency addendum
Your mortgage and inspection protections, and their deadlines.
Seller's Property Disclosure
What the seller knows, if they provide one. Not every seller does.
Lead paint forms
Required for homes built before 1978.
Licensee-Consumer Relationship Disclosure
Confirms I'm your buyer's agent, looking out for your interests.
Home Inspector Fact Sheet
Required information about home inspections.
How The First Two Weeks Usually Go
the offer
With an earnest money check, typically $1,000, held in escrow.
the response
The seller accepts, counters, or declines.
due diligence
Your home inspection and other checks. By day 8 or 9, we decide how to move forward.
the P&S
You sign the Purchase and Sale Agreement.
Every deal is different. We may shorten due diligence for a quick closing, or allow more time when you need it.
It's normal not to win the first offer. It's frustrating, I know. We'll learn from each one and come back stronger.
inspection to commitment.
Once your offer is accepted, your protections do their job. Here's what happens between the inspection and your lender's commitment.
the home inspection
Before the P&S. Be there and take notes. Add radon, pest, mold, lead, or Title V septic tests if needed. Real problems? We ask for repairs, a credit, or walk away within your contingency.
the P&S
Happy with the inspection? The attorneys draw up the full contract, including any repairs or credits we negotiated, and you review it before you sign.
your second deposit
5% of the price minus your earnest money, held in escrow until closing, where it becomes part of your down payment. Putting less than 5% down? This can be adjusted.
your own attorney
The lender's closing attorney represents the lender. A buyer's attorney isn't required, but I strongly recommend one to review the P&S, title, and condo documents.
the appraisal
Your lender's appraiser confirms the home is worth what you're paying. If it comes in low, we'll talk through your options.
mortgage commitment
Your lender rechecks your finances and commits by the date in your contract. If the loan falls through by then, your mortgage contingency protects your deposit.
Shop for homeowners insurance early. Your lender needs a policy in place before closing. And tell your lender before any big purchase, job change, or new credit.
keys in hand.
You made it. Here's what the last stretch looks like, and what you'll pay at closing.
The Last Stretch (Checklist)
What Closing Costs Include
- Lender fees: application, credit report, origination, underwriting
- Discount points: if you pay upfront for a lower rate
- Appraisal fee: independent valuation ordered by lender
- Attorney fees: for the lender's attorney and your own
- Title insurance: owner's title insurance protects you, and I recommend it
- Recording fees: municipal deed stamps paid to the county
- Prepaid escrow: a few months of taxes and insurance
Your Loan Estimate and Closing Disclosure show your exact numbers.
Scammers target homebuyers with fake wiring instructions. Before you send any money, call your attorney at a number you already know and confirm by phone. Never trust wiring instructions that arrive only by email.
what buyers ask me.
Real answers to the most common questions from first-time and relocating buyers across Greater Boston.
ask me.
Something else on your mind? Ask me anything, as often as you like. No question is too small, and that's what I'm here for.
closing day isn't goodbye.
I'm here for whatever comes next: a contractor recommendation, a market question a few years from now, or your next move. You'll hear from me on your home anniversary, with quarterly check-ins and an annual home value update.
Your First Week (Checklist)
Most of my business comes from past clients and the people they introduce me to. If you have a great experience, the best thank-you is sharing my name with someone thinking about a move.
This guide is general information, not legal, tax, or financial advice. Program rules and costs change, so confirm details with your lender and attorney.

Work With Marissa
Work With Marissa
Personalized guidance, strategic pricing, and dedicated one-on-one attention for buyers, sellers, landlords, and investors across Greater Boston.